Every small business has a limiting factor. It could be leads, cash flow, capacity, almost anything.
The Small Business Doctor diagnoses and develops a treatment plan for your bottleneck.
From business plan analysis to routine small business checkups to strategy sessions,
the Small Business Doctor provides the full-suite of strategic fractional CFO services.
Earnings per share (EPS) is a well-known financial metric that measures Net Income relative to the number of outstanding shares a company has. EPS is often used to compare one company to another.
Basic Earnings Per Share
EPS can be either basic or diluted. Basic EPS shows the portion of Net Income attributed to each outstanding share of common stock. Basic EPS does not consider any potential dilution of EPS from convertible securities, which can increase the number of shares. Basic EPS is widely used by analysts and investors.
Basic EPS = Income Available to Common Stock / Weighted Average Number of Shares Outstanding
Basic EPS is Income Available to Common Shareholders divided by the Weighted Average Number of Shares Outstanding.
Income Available to Common Stock = Net Income – Preferred Dividends
Both cumulative preferred stock dividends that are accrued in that year and non-cumulative preferred dividends that are declared in that year are deducted from Net Income.
The Weighted Average Number of Shares Outstanding takes into account events like stock issuances, stock dividends, treasury stock repurchases, and stock splits. For stock issuances and stock repurchases, you prorate them according to when these occurred during the year. If 100 shares were issued on May 1, then they are prorated at 8 months out of 12 months or two-thirds. If a treasury stock repurchase occurred on July 1, then those are prorated at half.
For stock splits and stock dividends, these are counted as if they were there all year. That’s because these don’t actually affect the value of equity. They merely redistribute it.
Diluted Earnings Per Share
Diluted EPS does consider this potential dilution of EPS from convertible securities. Diluted EPS shows what EPS would be if all convertible securities like stock options, convertible bonds, and convertible preferred stock were all converted to common stock.
Diluted EPS is calculated in case a company has a complex capital structure. If there are no dilutive securities, then Diluted EPS will equal Basic EPS. The most common dilutive securities are:
Convertible bonds
Stock options
Convertible preferred shares
Warrants
There are cases in which a convertible security is anti-dilutive, which means that if it were converted the earnings attributable to the convertible security are greater than the earnings that would be allocated to the additional common shares upon conversion. In these cases, anti-dilutive securities are removed from the calculation for Diluted EPS.
So, you need to assess for each class of convertible security whether it would be dilutive or anti-dilutive for this company based on its effect of Income Available to Common Shareholders and the Weighted Average Number of Outstanding Shares.
Convertible Bonds
When convertible bonds convert to shares, there are two income effects: Interest savings and an increase in income tax from the loss of the interest deduction.
Add: Interest savings = Bonds Carrying Value x Interest Rate of Bonds
Less: Income tax on interest = Interest savings x Tax rate
These income effects are compared to the effects of converting the bonds into shares.
New Share Amount = Amount of convertible bonds x Conversion ratio
Diluted EPS = (Income Available to Common Shareholders + Interest Savings – Taxes on Interest) / (Shares Outstanding + New Shares)
Convertible Preferred Shares
When preferred shares are converted to common stock, the preferred dividend payable is added back to income.
Preferred Dividend = Preferred stock par value x preferred stock dividend rate
The number of common shares from a preferred share depends on the company’s preferred share conversion ratio.
Options and Warrants
These do not affect the income part of the EPS ratio. They do however provide the company with cash from their exercise. To calculate the increase in common stock, presume that the company will use all of these proceeds to reacquire treasury stock. So, the increase in common stock is equal to the number of options. Then deduct the amount of repurchases that could fund.
Repurchased Shares = (New shares purchased x Exercise price) / Market price of a share
Disclosure
Companies are typically required by GAAP to report both Basic EPS and Diluted EPS. The following table summarizes these requirements.
Income from Continuing Operations
Disclose both Basic and Diluted EPS on the face of the Income Statement for Income from Continuing Operations
Net Income
Disclose both Basic and Diluted EPS on the face of the Income Statement for Net Income
Income from Discontinued Operations
Disclose both Basic and Diluted EPS either on the face or in the notes for Income from Discontinued Operations
Reconcile the numerator and denominator
Reconcile the numerator and denominator of the Basic and Diluted EPS for Income from Discontinued Operations to show the effects of each class of convertible securities.
Potentially Dilutive Securities
Disclose the potentially dilutive securities that were not included in the calculation of Diluted EPS because they were antidilutive.
Method used
Disclose the method used in the Diluted EPS computation for each class of dilutive convertible security
Over the years, I have happily and confidentially advised a wide range of clients from a plumber near Pittsburgh to a robotics startup to a multi-state pediatrics practice. I am always your primary point of contact and hold myself accountable for your success.
The initial consultation is always free. My billing goal is to always provide clients with a high return on investment when working with me irrespective of their budget.
I am not a salesman. I will only take on a client when I can provide genuine value for them. Reach out if you need expert advice, assistance or have a question.
Hi there! I'm Matt. I'm a Christian, husband and father of four. I'm a graduate of Calvin, Harvard, Cardiff and Johns Hopkins Universities. I have a PhD in Economics, an MBA in Finance and an MS in Data Analytics. I'm a numbers guy who can communicate well!
I began this service to work directly with the small and mid-sized business owners who grow our great country's economy. Since 1999, I've worked with owners across industries from high tech IT and robotics to small farmers and artists. I've also helped and advised nonprofits from churches to civic organizations.
I also served as a Finance Staff Officer and eventually as the National Division Chief for Measurement Research within the US Coast Guard. The research and methods I created there continue to guide strategic decisions to this day.
I enjoy being active outdoors, especially in wild lands. Hiking, biking and fly fishing are some of my favorite pastimes.
I also love dogs! I'm an AKC obedience evaluator, and I train service and therapy dogs.
Companies need to keep some amount of inventory. When I go to a home repair supplier, I expect them to have the copper pipe I need in stock. When I go to my local bakery, I expect them to have the macarons I crave in stock. When I go to my local grocer, I expect […]
Our culture values specialization. Having specialized skills often leads to outsized material benefits. It also often results in praise and social status. Consider the social recognition that would be given to a medical doctor who is a primary care family medicine doctor compared to that given to an orthopedic surgeon. They are both highly educated, […]
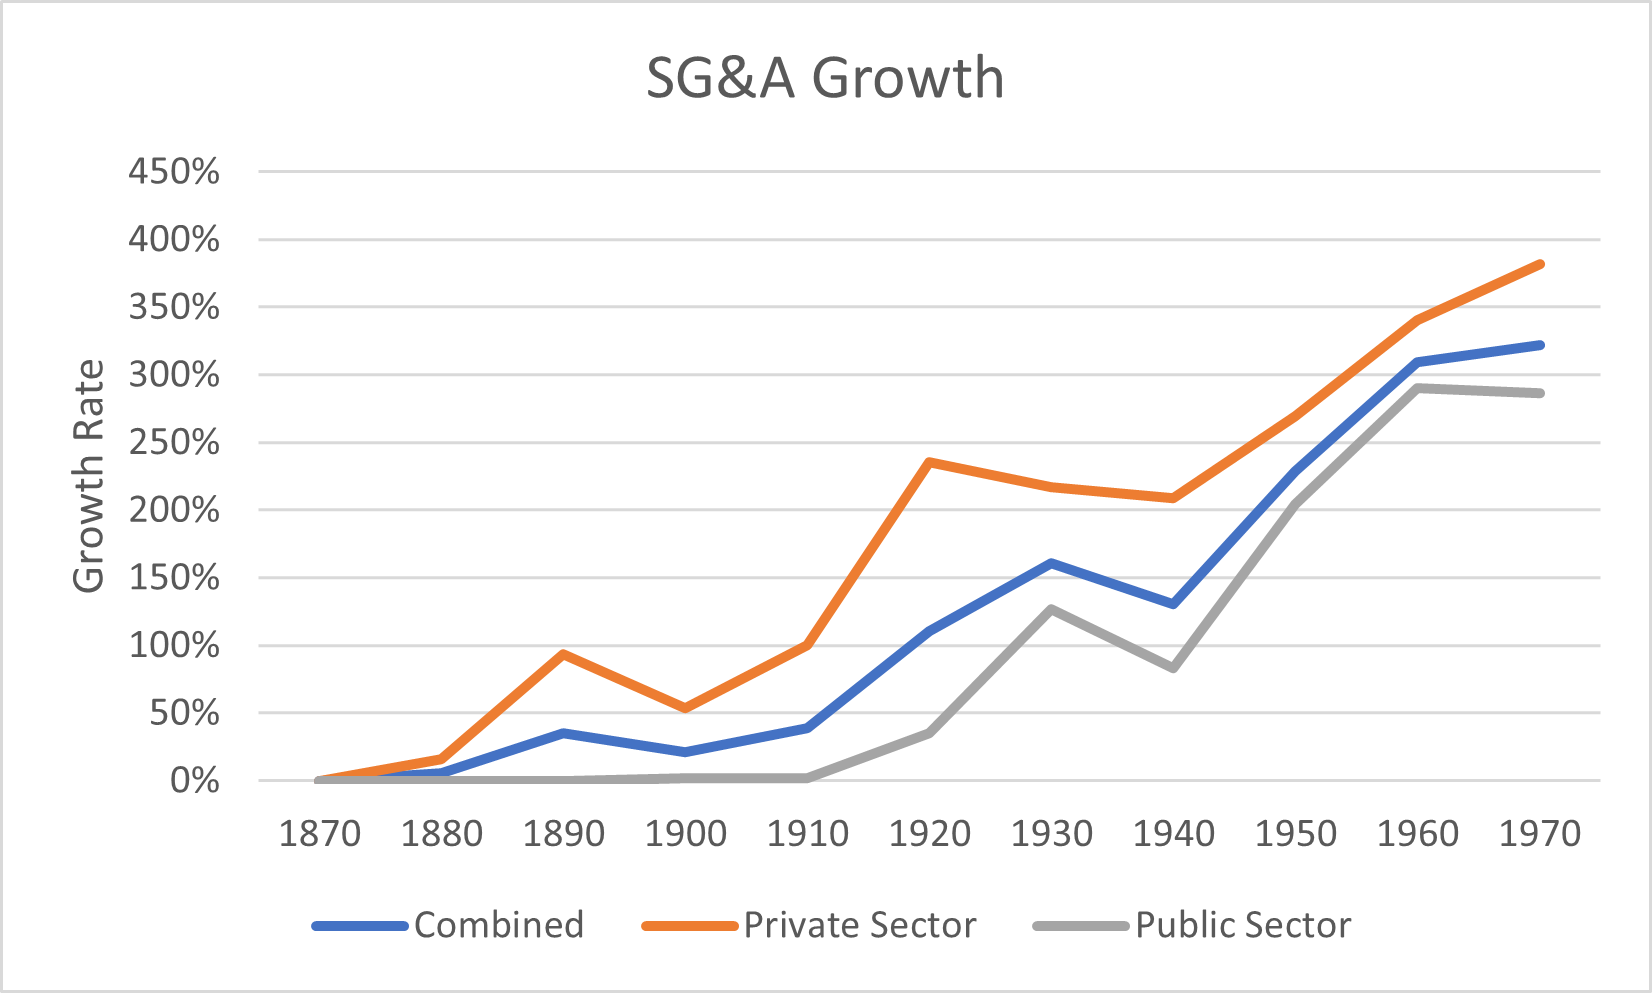
What Are Transaction Costs? Transaction costs are often overlooked in economics and textbook finance. In real life economics, however, they play a very significant role. In corporate finance, you can see many of a company’s transaction costs located in the selling and administrative categories within the Selling, General and Administrative (SG&A) section of their Income […]
During the Great Depression, British economist Ronald Coase wrote a famous essay on the nature of the firm or company. As with America at the time, many free-market economies were also enduring a severe and difficult economic depression. The Soviet Union, however, was growing to become a significant industrial economy. This led to a debate […]
Selling, General or Administrative Expenses One way to see how economic transaction costs are internalized within a company is in the SG&A Expense lines of a company’s income statement. All of the selling and administrative expenses are internalized transaction costs, and so is the insurance expense within the general expenses category. This is not the […]
Spams and scams have killed public polling. The person who would risk blowing up their phone or their bank account for the promise of a $20 gift card is not at all representative of the population at large.
Earnings per share (EPS) is a well-known financial metric that measures Net Income relative to the number of outstanding shares a company has. EPS is often used to compare one company to another. Basic Earnings Per Share EPS can be either basic or diluted. Basic EPS shows the portion of Net Income attributed to each […]

0 Comments
No comments yet. Be the first to comment